Tag: small business

  • How to Find a Business Partner: A Practical Guide

    How to Find a Business Partner: A Practical Guide

    How to Find a Business Partner: A Practical Guide

    Entrepreneurs who launch with the right co-founder are 2x more likely to successfully scale — here’s how to find yours without the costly mistakes.

    Why Choosing the Right Business Partner Is a High-Stakes Decision

    According to a 2025 Harvard Business School study, nearly 65% of startup failures stem from co-founder conflict — not bad products or lack of funding. That’s a sobering number, especially if you’re currently thinking about bringing someone on board to help grow your business.

    If you’ve ever watched a promising venture unravel because two owners stopped seeing eye-to-eye, you already know this risk is real. Whether you’re a solo entrepreneur looking for operational support or a small business owner who needs a partner with complementary skills, the decision to bring someone into your company deserves the same rigor you’d apply to any major financial investment.

    In this guide, you’ll learn exactly where to find a business partner in the US, what to look for before you commit, how to structure the relationship legally, and which red flags to avoid. Think of this as your step-by-step roadmap to making one of the most important calls of your entrepreneurial journey.

    What Is a Business Partner and How Does the Arrangement Work?

    A business partner is someone who shares ownership, responsibilities, and — depending on your structure — liability in a business venture. This is different from hiring an employee or bringing on a contractor. A partner typically holds an equity stake, meaning they own a percentage of the business and are entitled to a share of profits and losses.

    In the US, business partnerships are commonly structured in one of three ways:

    • General Partnership (GP): Both partners share equal management responsibilities and personal liability for business debts.
    • Limited Partnership (LP): One partner manages operations (general partner) while others contribute capital but have limited liability (limited partners).
    • LLC with Multiple Members: Partners form a Limited Liability Company together, protecting personal assets while sharing ownership. This is the most popular structure for small business co-ownership today.

    The IRS treats partnerships as pass-through entities, meaning profits and losses flow directly to the partners’ individual tax returns — a critical detail when planning your finances. According to the IRS, there were over 4.2 million partnership returns filed in the US in 2024, reflecting just how common this arrangement remains.

    Knowing the structure options upfront allows you to have informed conversations with potential partners before either of you commits to anything.

    Key Benefits of Having the Right Business Partner

    When the fit is right, a business partnership can be one of the most powerful accelerators for your company’s growth. Here’s what you stand to gain:

    Complementary skill sets. If you’re strong in sales and marketing but weak in operations or finance, a partner who fills those gaps can dramatically reduce your risk. Research from Startup Genome found that startups with two co-founders raise 30% more investment capital than solo founders.

    Shared financial burden. Starting or scaling a business requires capital. A partner can contribute funds, which reduces how much you need to borrow or give up to outside investors. According to the Federal Reserve’s 2025 Small Business Credit Survey, 43% of small business applicants cited insufficient collateral as a barrier to funding — sharing the load with a partner can ease that pressure.

    Accountability and resilience. Running a business solo can be isolating. A good partner provides a built-in sounding board, keeps you accountable, and helps carry the emotional weight during difficult stretches — a factor that’s often underestimated but consistently cited by successful entrepreneurs.

    Operational continuity. If you get sick, need time off, or face a personal emergency, a partner ensures the business doesn’t come to a standstill. This is especially important for service-based businesses and client-facing operations.

    The key word throughout all of this is right. A mismatched partner erases every one of these benefits and introduces new, expensive problems.

    How to Find a Business Partner: Step-by-Step

    Finding a trustworthy, aligned business partner doesn’t happen by accident. Here’s a proven process you can follow:

    1. Define what you need before you search. Write out your own strengths and weaknesses honestly. Then list the specific skills, industry experience, and personality traits you need in a partner. Don’t start looking until you know what you’re looking for.
    2. Tap your professional network first. According to SCORE, a national nonprofit supported by the US Small Business Administration (SBA), over 70% of successful business partnerships begin within existing professional circles — former colleagues, clients, or industry peers. Start there before looking at strangers.
    3. Use co-founder matching platforms. Platforms like CoFoundersLab, Indie Hackers, and Founder2be are designed specifically to connect entrepreneurs. LinkedIn is also a powerful tool — search for professionals in your industry and reach out with a specific, well-crafted message about what you’re building.
    4. Attend entrepreneurship events and accelerators. Organizations like your local SBA office, SCORE chapter, or regional Chamber of Commerce regularly host events that bring entrepreneurs together. Incubators and accelerators like Y Combinator, Techstars, and 500 Startups also facilitate co-founder connections through their programs.
    5. Run a trial period before formalizing anything. Before signing any legal documents, work together on a defined project for 60 to 90 days. Pay attention to how they handle pressure, communicate, and follow through on commitments. This trial period is non-negotiable.
    6. Conduct thorough due diligence. Check references. Look at their financial history if the business will involve shared finances. Run a background check through a reputable service. Ask hard questions about past business relationships and why they ended.
    7. Hire a business attorney to draft a partnership agreement. This document should cover equity split, roles and responsibilities, decision-making authority, compensation, buy-sell provisions (what happens if one partner wants out), and dispute resolution processes. The cost of a solid partnership agreement — typically $1,500 to $5,000 — is a fraction of what a legal dispute costs later. For LLC formation guidance, see our full breakdown on Small Business Exit Strategy: How to Plan Your Way Out.

    Costs, Fees, and Risks You Need to Understand

    A business partnership is not without its costs — financial and otherwise. Here’s what to budget for and watch out for:

    Legal fees: Drafting a partnership agreement or LLC operating agreement with a business attorney typically costs between $1,500 and $5,000 depending on complexity and your location. Skipping this step to save money is one of the most expensive mistakes entrepreneurs make.

    Equity dilution: Giving up equity means giving up future profits. If your business eventually sells for $2 million and your partner holds 40%, that’s $800,000 they walk away with. Know exactly what you’re offering before negotiations begin.

    Tax complexity: Partnership tax returns (Form 1065) are more complex than sole proprietor filings. You’ll likely need a CPA, which can add $500 to $2,500 or more annually to your accounting costs depending on business complexity.

    Personal liability in a general partnership: In a standard general partnership, both partners are personally liable for business debts and legal judgments. This means your personal assets — home, savings, car — could be at risk if things go wrong. Forming an LLC instead provides a layer of protection.

    Relationship risk: If the partnership breaks down, you may face legal disputes, loss of key operational knowledge, and damage to customer relationships. Having a well-structured buyout clause in your agreement is your best protection. You may also want to revisit our guide on Small Business Exit Strategy for planning ahead.

    Common Mistakes to Avoid When Choosing a Business Partner

    The most costly partnership mistakes are almost always avoidable. Watch out for these:

    1. Partnering based on friendship alone. Friendship and business compatibility are two entirely different things. Just because you trust someone personally doesn’t mean you share the same work ethic, financial risk tolerance, or vision for the company. Many friendships have been permanently destroyed by business partnerships that weren’t built on professional alignment.

    2. Skipping a formal partnership agreement. A handshake deal or a vague email chain is not a legally binding agreement. Without a formal document, disputes about profit distribution, ownership percentage, and exit terms become expensive legal battles. The SBA strongly recommends all business partnerships be formalized in writing before any money changes hands.

    3. Splitting equity 50/50 without thinking it through. A 50/50 split sounds fair but creates a deadlock risk — if you and your partner disagree on a major decision and neither holds controlling interest, the company can grind to a halt. Consider slight adjustments (51/49) or include a formal tie-breaking process in your agreement.

    4. Ignoring financial red flags. If a potential partner has a history of unpaid debts, failed businesses with unresolved creditor disputes, or poor personal credit, those signals matter. According to the CFPB, financial stress is one of the leading contributors to business partner disputes. Do your homework.

    5. Failing to align on long-term vision. If you want to build a lifestyle business and your partner wants to scale fast and sell in five years, that misalignment will eventually blow up the relationship. Have the hard conversations about exit goals, growth pace, and reinvestment strategy before you start — not two years in.

    Alternatives to a Traditional Business Partner

    A full equity partnership isn’t always the right move. Depending on your situation, one of these alternatives might serve you better:

    Key hire instead of a partner. If you need operational support but aren’t ready to give up equity, hiring a highly skilled employee or executive — possibly with a performance-based bonus or small profit share — can fill the gap without the legal complexity of a partnership. This is often the right call in the early stages when cash flow is tight.

    Business advisor or fractional executive. Many experienced entrepreneurs and executives offer fractional services — meaning they work with your company part-time for a monthly retainer. A fractional CFO, COO, or CMO can bring the expertise you need without permanent equity commitment. Retainers typically range from $2,000 to $10,000 per month depending on the role and scope.

    Strategic joint venture. Instead of merging ownership in a single entity, two businesses can form a joint venture for a specific project or market opportunity. This allows you to leverage another company’s resources, distribution, or expertise without giving up equity in your core business. Joint ventures are governed by a separate agreement and are time-limited or project-specific.

    Each of these alternatives has trade-offs. A hire costs salary but preserves ownership. A fractional executive costs cash but offers flexibility. A joint venture requires careful legal structuring. Evaluate which model matches your current growth stage and financial position.

    Frequently Asked Questions

    Q: What percentage of equity should I give a business partner?
    A: There’s no universal answer, but equity should reflect each partner’s contribution — capital invested, skills brought, risk assumed, and time committed. Common splits range from 50/50 to 70/30. Work with a business attorney to model out scenarios before making an offer.

    Q: How do I protect myself if a partnership goes bad?
    A: A well-drafted partnership or LLC operating agreement with a buyout clause is your primary protection. Include provisions for how a departing partner’s shares are valued and purchased, and add a non-compete clause to prevent a former partner from immediately competing against you.

    Q: Can I find a business partner online?
    A: Yes — platforms like CoFoundersLab, LinkedIn, and Indie Hackers are widely used. However, vet every candidate thoroughly. Treat it like a hiring process with background checks, reference calls, and a trial work period before formalizing anything.

    Q: Do I need a lawyer to form a business partnership?
    A: Technically no, but practically yes. The IRS and most states have minimal formal requirements to create a general partnership, but the absence of a legal agreement is the single biggest source of costly disputes. Always hire a business attorney to draft your agreement.

    Q: How is a business partnership taxed in the US?
    A: Partnerships file an informational return using IRS Form 1065, and each partner receives a Schedule K-1 showing their share of income, deductions, and credits. Each partner then reports their K-1 income on their individual tax return. Partners are also subject to self-employment tax on their share of business income. Consult a CPA for your specific tax situation.

    The Bottom Line: Choose Your Business Partner Like You’d Choose a Business

    Finding the right business partner is one of the highest-leverage decisions you’ll make as an entrepreneur. Done well, it can double your chances of success, accelerate growth, and make the journey significantly less lonely. Done poorly, it can cost you years of effort, thousands of dollars in legal fees, and — in the worst cases — your business itself.

    The process requires honest self-assessment, disciplined vetting, a formal legal agreement, and clear alignment on the big-picture vision. Don’t rush it. Don’t let friendship override professional judgment. And don’t skip the paperwork.

    Your next step: write out your own skill gaps and business goals this week. Then look at your existing professional network for two or three people who fill those gaps. That’s where most great partnerships begin. And if you’re building your financial infrastructure as you grow, check out our guide on Best Business Credit Cards for Small Business in 2026 to make sure your funding tools are in place.

    Consulting a business attorney and a CPA before finalizing any partnership arrangement is strongly recommended — the upfront cost is always less than the cost of fixing a poorly structured deal.


    Financial Disclaimer: This article is for educational purposes only and does not constitute financial, tax, or investment advice. Always consult a licensed financial advisor, CPA, or attorney before making financial decisions.
  • How to Build an MVP for Your Startup in 2026

    How to Build an MVP for Your Startup in 2026

    What Is a Minimum Viable Product — and Why Most Entrepreneurs Get It Wrong

    Founders who skip the MVP stage waste an average of $50,000 or more building products nobody wants — here’s how to avoid that trap.

    According to CB Insights, the number one reason startups fail is building something the market simply doesn’t need. That single mistake — launching a full product before testing demand — has killed more businesses than bad timing, poor funding, or tough competition combined.

    A Minimum Viable Product, or MVP, is the fastest, cheapest version of your business idea that still delivers real value to real customers. It’s not a rough draft or a broken prototype — it’s a focused tool for learning whether your core assumption is right before you burn through savings or investor capital.

    In this guide, you’ll learn exactly what an MVP is, how to build one on a lean budget, what mistakes sink most first-time founders, and how to know when your MVP is ready to evolve into a scalable product. Whether you’re launching a SaaS tool, a physical product, or a service business, the MVP framework applies — and it can save you months of wasted effort.

    What Is an MVP and How Does It Work?

    The term "Minimum Viable Product" was popularized by Eric Ries in his 2011 book The Lean Startup, but the concept has become a cornerstone of modern entrepreneurship — from Y Combinator-backed startups to bootstrapped side hustles.

    An MVP is the smallest version of your product that can be released to real customers to collect meaningful feedback. Think of it as a controlled experiment: you’re testing one core hypothesis — usually "will people pay for this?" — with the minimum resources possible.

    Here’s how the process works in practice:

    • Identify your riskiest assumption. Every business idea is built on assumptions. Your MVP should test the most critical one first.
    • Build only what proves or disproves that assumption. Everything else is a distraction at this stage.
    • Release it to a small group of real users. Not friends, not family — actual potential customers.
    • Measure behavior, not opinions. What people do matters far more than what they say they’ll do.
    • Iterate or pivot based on data. An MVP without a learning loop is just a prototype gathering dust.

    It’s worth noting: an MVP doesn’t have to be software. Dropbox’s MVP was a demo video. Airbnb’s MVP was a simple webpage renting out air mattresses in a San Francisco apartment. Zappos’ founder tested shoe demand by photographing local store inventory and listing the photos online — only buying the shoes when someone actually ordered. These are among the most famous examples of MVP thinking that reshaped entire industries.

    According to the Kauffman Foundation, the median cost to start a business in the US is around $30,000 — but founders who validate ideas before building spend significantly less and reach profitability faster.

    Key Benefits of Building an MVP First

    Skipping the MVP stage feels tempting when you’re passionate about your idea. But the financial and strategic case for starting lean is overwhelming.

    1. You preserve capital. Building a full product before validation is one of the most expensive mistakes an entrepreneur can make. An MVP lets you spend $5,000–$15,000 testing demand instead of $100,000+ building features no one uses.

    2. You reduce investor risk — and improve your pitch. According to the NVCA (National Venture Capital Association), investors increasingly expect founders to show traction or validated demand before writing a check. An MVP with 50 paying customers is worth more in a pitch deck than a polished product with zero revenue.

    3. You learn what customers actually want. Most founders discover that the features they assumed were essential aren’t what customers value most. An MVP surfaces this early, while corrections are still affordable.

    4. You build faster. Constraints force clarity. When you can only build one thing, you figure out quickly what matters most. Many founders report their MVP shipped in 4–8 weeks when a "full product" would have taken 12–18 months.

    5. You create early advocates. Early users who help shape a product become loyal customers and word-of-mouth evangelists. This is a marketing advantage money can’t easily buy later.

    If you’ve already validated your business idea, the next logical step is building an MVP — not a finished product. These two stages are closely linked, and confusing them costs founders time and money.

    How to Build an MVP: A Step-by-Step Framework

    Building an MVP isn’t just about cutting features — it’s about making smart choices on what to include and what to defer. Here’s a practical process that works across industries.

    Step 1: Define your one core value proposition. Write one sentence that completes this: "We help [target customer] solve [specific problem] by [unique approach]." If you can’t finish that sentence clearly, you’re not ready to build yet.

    Step 2: Map your riskiest assumptions. List every assumption your business idea depends on. Rank them by importance and uncertainty. The riskiest assumption — the one that would kill the business if wrong — is what your MVP must test.

    Step 3: Choose your MVP type. Not all MVPs are software builds. Common MVP formats include:

    • Landing page MVP: A single-page website that describes the product and captures email signups or pre-orders. Cost: $200–$500.
    • Concierge MVP: You manually deliver the service before automating it. Great for service businesses and SaaS ideas. Cost: Your time.
    • Wizard of Oz MVP: Users think they’re using an automated product, but humans are fulfilling the service behind the scenes.
    • Prototype MVP: A clickable mockup built with tools like Figma that simulates the product experience without actual functionality.
    • Pre-sale MVP: You accept payment before the product exists. If people won’t pay for a description, they won’t pay for the real thing.

    Step 4: Set a success metric before you launch. Define what "success" looks like in concrete terms. For example: "If 10 out of 50 people who see the landing page sign up with a credit card, we proceed." Without a threshold set in advance, you’ll rationalize any result.

    Step 5: Get it in front of real potential customers — fast. Use channels you already have access to: LinkedIn, local business groups, industry forums, Reddit communities, or direct outreach. Aim for 50–200 real interactions in the first 30 days.

    Step 6: Measure what matters. Track behavior over opinions. Key MVP metrics include conversion rate, activation rate (did users complete the core action?), retention (did they come back?), and willingness to pay.

    Step 7: Decide — iterate, pivot, or stop. If data supports your hypothesis, build more. If it partially supports it, refine the offer. If it doesn’t, pivot to a new assumption or consider whether this market is worth pursuing. Stopping early is not failure — it’s smart capital allocation.

    Costs, Fees, and Real Financial Risks

    One of the biggest misconceptions about MVPs is that they’re always cheap. They’re cheaper than full builds — but there are still real costs to plan for.

    Technology costs: A basic no-code MVP using tools like Webflow, Bubble, or Shopify can cost $50–$300 per month in platform fees. Custom development MVPs range from $8,000–$40,000 depending on complexity and whether you hire a US-based or offshore team.

    Customer acquisition costs: You need real users to test with. Paid ads (Google, Meta) for MVP testing typically cost $500–$3,000 for meaningful data. Organic outreach takes longer but costs less.

    Legal basics: Even at the MVP stage, you should have basic terms of service, a privacy policy, and — if you’re collecting payments — proper LLC or business entity structure. Forming an LLC costs $50–$500 depending on your state. Skipping this is a liability risk many first-time founders underestimate.

    Opportunity cost: The biggest hidden cost of a poorly run MVP is time. Founders who spend 12 months "refining" an MVP that never gets real user feedback are burning their most valuable resource.

    Tax implications: Business expenses tied to your MVP — software subscriptions, contractor payments, advertising — are generally deductible as business expenses under IRS rules. Keep receipts and track everything from day one. A basic accounting setup, even at the pre-revenue stage, prevents costly headaches later. Our guide on best accounting software for small businesses covers affordable options that work well at this stage.

    Common MVP Mistakes That Sink Startups

    Even founders who understand the MVP concept often make costly mistakes in execution. Here are the most common ones — and how to avoid them.

    Mistake 1: Building too much. The "M" in MVP stands for minimum, but most founders default to building their ideal product and calling it an MVP. If your MVP takes more than 8–12 weeks to ship, it’s probably not minimal enough. Cut ruthlessly until only the core hypothesis-testing feature remains.

    Mistake 2: Testing with the wrong people. Getting positive feedback from friends, family, or fellow entrepreneurs is almost meaningless. You need feedback from people who fit your target customer profile and have no social obligation to be kind. Qualitative feedback from 10 real strangers beats glowing reviews from 50 people who care about your feelings.

    Mistake 3: Measuring vanity metrics. Page views, social media followers, and app downloads feel good but rarely predict business viability. Focus on retention, activation, and willingness to pay. A product with 200 users and a 40% month-over-month retention rate is in a far stronger position than one with 10,000 downloads and 2% retention.

    Mistake 4: Failing to set a clear decision threshold in advance. Many founders run MVP experiments with no clear criteria for what success looks like. Without a predetermined threshold, every result gets rationalized. Before you launch, write down: "We will proceed if X. We will pivot if Y. We will stop if Z."

    Mistake 5: Treating the MVP as the end goal. An MVP is a learning vehicle, not a finished product. Founders who stop iterating after initial validation miss the real opportunity — using what they’ve learned to build something significantly better.

    Alternatives to the Traditional MVP Approach

    The classic MVP framework isn’t the only way to validate a business idea. Depending on your industry, budget, and timeline, these alternatives may be a better fit.

    1. Pilot Program or Beta Launch
    Instead of a stripped-down product, you launch a full (but limited-access) version to a small group of vetted customers. This approach works well for B2B SaaS and service businesses where customers expect a more polished experience. Pro: Higher-quality feedback. Con: More expensive and time-consuming to set up.

    2. Crowdfunding Campaign
    Platforms like Kickstarter or Indiegogo let you test demand and raise capital simultaneously. If your campaign hits its funding goal, you’ve validated demand — and pre-funded production. Pro: Market validation plus cash. Con: Requires strong marketing and a compelling story to stand out. Failing publicly can also damage brand perception.

    3. Consulting or Done-For-You Services
    Some of the best product businesses started as service businesses. You deliver results manually for 5–10 clients, learn exactly what they need, then build a product or tool to systematize that service. This approach generates revenue while you validate. Pro: Cash flow positive from day one. Con: Service delivery is time-intensive and doesn’t scale until the product is built.

    If you eventually need outside funding to grow beyond the MVP stage, having a clear business plan will be essential. Understanding the full scope of your venture before approaching lenders or investors positions you for stronger outcomes.

    Frequently Asked Questions

    How long should it take to build an MVP?
    In most cases, a true MVP should take 4–12 weeks to launch, depending on complexity. If you’re past the 3-month mark with no real users testing the product, you’ve likely overbuilt. Aim for something shippable, not something perfect.

    Do I need technical skills to build an MVP?
    Not necessarily. No-code tools like Bubble, Webflow, Glide, and Shopify allow non-technical founders to build functional MVPs without writing a single line of code. Many successful startups — including Groupon and Craigslist — launched with remarkably simple tech stacks.

    Should I charge for my MVP?
    Generally speaking, yes — if charging is part of your business model. Getting someone to use a free product proves very little. Getting someone to pay proves demand. Even a small payment ($1, $9, $49) is a meaningful signal that your core value proposition resonates.

    What if my MVP fails?
    A failed MVP isn’t a failed business — it’s valuable data. Most successful companies pivoted significantly from their original MVP. Instagram started as a location-sharing app. Slack was built to support an internal game. Failure at the MVP stage is far less costly than failure after a full product launch.

    How many users do I need to validate an MVP?
    There’s no universal number, but most experts suggest aiming for at least 20–50 paying customers or meaningful interactions before drawing conclusions. For B2B products, even 5–10 committed pilot customers can be enough to validate a hypothesis at the enterprise level.

    Final Thoughts: Build Less, Learn More, Waste Nothing

    The MVP framework isn’t just a startup buzzword — it’s one of the most financially responsible strategies available to entrepreneurs. By testing your core assumption with the smallest possible investment, you protect your capital, sharpen your product, and dramatically increase your odds of building something people actually want and will pay for.

    The founders who succeed aren’t the ones with the biggest budgets or the most ambitious visions — they’re the ones who learn fastest and adapt most efficiently. An MVP is the tool that makes that possible.

    Your next step: write down the single riskiest assumption behind your business idea. Then ask yourself — what’s the cheapest, fastest way to test whether that assumption is true? That’s your MVP. If you’re ready to take the idea further, consider building out your team and operational systems once early validation is confirmed.

    This article is for educational purposes only and does not constitute financial, tax, or investment advice. Always consult a licensed financial advisor, CPA, or attorney before making financial decisions.
  • How to Validate a Business Idea Before You Spend a Dollar

    How to Validate a Business Idea Before You Spend a Dollar

    Entrepreneurs who validate their ideas before launching are 2.5x more likely to build a profitable business — yet most skip this step entirely.

    Why Most Business Ideas Fail Before They Even Start

    According to the U.S. Bureau of Labor Statistics, approximately 20% of new businesses fail within the first year — and nearly 45% close before reaching their fifth anniversary. But here’s what most people don’t talk about: the majority of those failures weren’t caused by bad execution. They were caused by building something nobody wanted.

    Think about Marcus, a 38-year-old project manager from Austin who spent $22,000 developing a mobile app for local gym-goers. He quit his job, hired a developer, and launched with confidence. Twelve months later, he had 47 downloads and no revenue. The painful truth? He never asked a single potential customer if they’d actually pay for it.

    Validating your business idea means testing whether real people will pay real money for what you’re planning to offer — before you invest significant time or capital. In this guide, you’ll learn a practical, step-by-step framework to validate any business concept on a tight budget, so you can build with confidence instead of guessing in the dark.

    What Business Idea Validation Really Means

    Business idea validation is the process of confirming that a market need exists, that your target customers recognize the problem you’re solving, and — most critically — that they’re willing to pay for your solution.

    It’s different from market research. Market research tells you what the data says. Validation tells you what real humans actually do with their wallets.

    According to CB Insights’ analysis of startup failures, the number one reason startups fail (cited in 35% of post-mortems) is "no market need." That’s not a cash flow problem or a team problem — it’s a validation problem. Founders built something before confirming anyone wanted it.

    Validation applies whether you’re launching a SaaS product, a local service business, an e-commerce store, or a consulting practice. The tools and methods vary, but the core question is always the same: Will people pay for this?

    This matters in the US context especially because the American market is competitive and relatively saturated in most verticals. Standing out requires a clear value proposition that resonates — and you can only know if it resonates by testing it directly.

    Key Benefits of Validating Before You Invest

    Skipping validation feels efficient. In reality, it’s the most expensive mistake an entrepreneur can make. Here’s what proper validation actually gives you:

    You save money. The average US small business owner invests between $10,000 and $80,000 in their first year, according to the Kauffman Foundation. Validating before spending can protect the bulk of that investment. A failed validation experiment might cost you $500. A failed launch can cost you everything.

    You get real customer language. Talking to potential customers before you build gives you the exact words they use to describe their pain. That language becomes your marketing copy, your pitch, and your product roadmap. It’s market research and copywriting rolled into one.

    You reduce emotional bias. Every entrepreneur falls in love with their idea. Validation forces you to test that love against reality — before you’ve committed your savings and your identity to it.

    You attract better funding. If you ever approach investors or apply for a small business loan, early traction from validation experiments is compelling evidence. It shows you’re building something the market wants — not something you think the market wants.

    You build faster. Counterintuitively, validating slows you down at the start and dramatically speeds you up later. You stop building features nobody uses. You stop pivoting because you already know what works.

    How to Validate Your Business Idea: Step-by-Step

    Here’s a practical framework any entrepreneur can execute, regardless of industry or budget.

    Step 1: Define the Problem Sharply

    Write one sentence that describes the problem you’re solving, who has it, and why existing solutions fall short. If you can’t do this in one sentence, your idea isn’t clear enough yet.

    Example: "Freelance graphic designers in the US lose an average of 8 hours per week on invoicing and client follow-ups because existing tools weren’t built for their workflow."

    Be specific about your target customer. "Small business owners" is not a target market. "Solo freelance designers earning $50K–$120K annually who use Figma" is a target market.

    Step 2: Identify Your Riskiest Assumption

    Every business idea rests on assumptions. Your job is to find the one assumption that, if proven wrong, kills the entire concept. This is your riskiest assumption — and it’s what you validate first.

    Common riskiest assumptions include:

    • Customers actually experience this problem (not just occasionally, but painfully)
    • Customers will pay money to solve it (not just say they would)
    • Your proposed solution actually solves the problem better than alternatives
    • You can reach these customers affordably enough to build a profitable business

    Don’t validate your second-riskiest assumption first. Start with the one that hurts most if you’re wrong.

    Step 3: Talk to 20 Real Potential Customers

    This is the most important step — and the one most entrepreneurs skip because it feels uncomfortable. You need to conduct genuine problem interviews, not pitch sessions.

    The goal is not to sell your idea. The goal is to understand whether the problem exists and how much pain it causes. Ask questions like:

    • "Tell me about the last time you dealt with [problem]. What happened?"
    • "How are you handling it today? What do you hate about that?"
    • "Have you paid for any tools or services to solve this? What did you spend?"
    • "If this problem disappeared tomorrow, what would that mean for your business?"

    Find these people through LinkedIn, Reddit communities, local business groups, industry Facebook groups, or your existing network. Twenty conversations is the minimum. Thirty is better.

    Take verbatim notes. Patterns in language, emotion, and spending behavior are your data.

    Step 4: Build the Simplest Possible Version (MVP)

    An MVP — Minimum Viable Product — is not a half-baked version of your full idea. It’s the smallest possible thing that can test your riskiest assumption and deliver real value to a real customer.

    For a software product, your MVP might be a manual process done over email before you write a single line of code. For a consulting service, it might be one free project done for a local business in exchange for a detailed testimonial. For a physical product, it might be a landing page with a "Buy Now" button that collects emails and tells you if anyone is interested.

    The question your MVP answers is: "Will someone engage with this enough to take action?"

    Step 5: Ask for Money (or a Commitment)

    This is where validation becomes real. Enthusiasm is cheap. Dollars aren’t.

    If your business model involves payment, ask for it — even at a discount or as a pre-order. A customer who pays $97 for early access is infinitely more valuable as a signal than 500 people who said "I’d definitely use that."

    If direct payment isn’t possible yet, look for high-commitment behaviors: email list sign-ups with a credit card entered, a letter of intent from a B2B prospect, or a social media following built around the specific problem you’re solving.

    Set a concrete validation threshold before you start. Something like: "If 10 people pre-order at $149, I’ll build this." Define success before you test so you’re not moving goalposts based on wishful thinking.

    Step 6: Analyze Results and Decide

    Once you’ve run your validation experiment, you’ll land in one of three places:

    • Clear signal: People paid or committed enthusiastically. Proceed and build.
    • Weak signal: Some interest, but not enough. Adjust your target customer, pricing, or positioning and retest.
    • No signal: People were polite but didn’t act. This is the most valuable outcome — you just saved yourself potentially tens of thousands of dollars.

    A "no" from the market isn’t failure. It’s information. Pivot the idea, niche down further, or walk away and find a better problem to solve.

    Costs, Risks, and What Validation Can’t Tell You

    Validation is powerful, but it has limits you need to understand before relying on it too heavily.

    Cost of validation: Done right, a basic validation experiment costs between $0 and $1,000. Tools like a simple landing page (Carrd.co, $19/year), a Google Ads test campaign ($200–$500 for targeted traffic), and Calendly for booking interviews (free tier) are all you need. Some entrepreneurs spend nothing — just LinkedIn outreach and a Google Form.

    Risk of false positives: Friends and family will tell you your idea is great. People in interviews will say they’d pay even when they won’t. This is called "polite enthusiasm" — and it’s dangerous. Mitigate it by only counting actual payments or hard commitments, never verbal support.

    Risk of false negatives: Sometimes a great idea fails validation because your message was unclear, you targeted the wrong customer segment, or you priced it wrong. A failed experiment doesn’t automatically mean a bad idea — it means that specific test didn’t work. Reframe, adjust, and retest before walking away.

    What validation can’t tell you: It can confirm demand exists. It can’t predict scale, long-term retention, or competitive response. You still need to manage your cash flow carefully — and if your business grows, having systems in place for accounting and financial tracking becomes critical early on.

    Tax and legal note: Even during validation, keep clean financial records of any revenue collected. The IRS requires you to report business income regardless of how early-stage your business is. Consult a licensed CPA to understand how pre-launch activities affect your tax situation.

    Common Mistakes to Avoid When Validating

    Mistake #1: Validating your solution instead of the problem. Most founders pitch their solution and ask "Would you use this?" That’s backwards. Validate the pain first. If the pain is real and severe, customers will help you design the solution. Jumping to "here’s my product" skips the most important half of the conversation.

    Mistake #2: Counting interest as validation. A thousand people signing up for your waitlist is not validation. Ten people paying $99 is. The leap from "interested" to "paying customer" is massive — and most entrepreneurs dramatically overestimate how many interested people will convert. Always push for a financial commitment before declaring your idea validated.

    Mistake #3: Talking only to people who already agree with you. Confirmation bias is lethal in entrepreneurship. If you only interview people in your network who support your vision, you’ll get a skewed picture. Actively seek out skeptics — people who don’t have the problem, who use a competitor happily, or who think your solution is too expensive. Their objections are gold.

    Mistake #4: Setting validation thresholds too low. "If 2 people pre-order, I’ll build it" is not a threshold — it’s wishful thinking. Set your bar based on the economics of your business. If you need 100 paying customers to break even, validate with at least 10–15 pre-orders or signed letters of intent from target customers before investing in infrastructure.

    Mistake #5: Skipping validation because "the idea is obvious." The more certain you feel, the more important validation becomes. Certainty is often emotion dressed up as logic. Even experienced entrepreneurs who’ve built successful companies before can misjudge market demand. The process exists precisely for moments when you feel like you already know the answer.

    Alternatives: Other Ways to Test Your Concept

    If traditional customer interviews and landing page tests don’t fit your model, consider these alternatives:

    Concierge MVP: Manually deliver your service or product to 3–5 early customers before automating anything. This is especially effective for service businesses, marketplaces, and SaaS tools with workflow components. You learn exactly what customers value — and what they ignore — before building anything permanent. The downside is it doesn’t scale, but that’s the point at this stage.

    Pre-sale campaigns: Platforms like Kickstarter or Indiegogo let you test physical product ideas with real pre-orders before manufacturing. This works especially well for consumer products. According to Kickstarter’s data, product campaigns that hit 30% of their goal in the first 48 hours have an 89% chance of fully funding. The risk: you’re now committed to delivering, which adds execution pressure.

    Paid ad testing: Run a small Facebook or Google Ads campaign ($200–$500) driving traffic to a simple landing page. Measure click-through rates, email opt-ins, and "buy now" clicks (even if you’re not actually charging yet). This gives you data on message resonance and customer acquisition costs before you build a product. Pair this with solid CRM tools to track and follow up with every lead you generate during the test.

    Frequently Asked Questions

    How long should business idea validation take?
    In most cases, a solid validation cycle takes 4–8 weeks. Two weeks for customer interviews, two weeks to build and launch a minimal experiment, and another week or two to analyze results and decide. Don’t rush it — but don’t let it drag into months. At some point, analysis paralysis becomes its own kind of failure.

    Do I need money to validate a business idea?
    Not necessarily. Customer interviews cost nothing but your time. A basic landing page costs $19–$50/year. A small ad budget of $200–$500 dramatically speeds up the process but isn’t mandatory. The most important validation tool — honest conversations with real potential customers — is completely free.

    What if my validation fails? Should I give up?
    Not automatically. A failed experiment is feedback, not a final verdict. Ask yourself: did I reach the right customer? Was my messaging clear? Was the price point appropriate? Often, one or two adjustments can turn a failed test into a successful one. Give yourself a rule: validate a second time with adjustments before walking away entirely.

    Can I validate a B2B business idea the same way as a consumer idea?
    The principles are the same, but the process looks different. B2B validation often uses discovery calls, letters of intent, or pilot agreements rather than pre-orders or landing pages. Decision cycles are longer, and you may need to get past a gatekeeper before reaching the actual buyer. Budget more time — 8–12 weeks — for thorough B2B validation, and aim for at least 3–5 signed pilot agreements before investing in product development.

    How do I know when I’ve validated enough?
    You’ve validated enough when you’ve hit your pre-defined threshold (e.g., 10 paying pre-orders, 5 signed letters of intent, 3 pilot agreements) and you have a clear, repeatable process for finding and converting your target customer. If you can explain in two sentences who your customer is, what pain you solve, and why they choose you over alternatives — and you have evidence to back it up — you’re ready to build.

    The Bottom Line: Test First, Build Second

    The most expensive thing you can do as an entrepreneur is build something nobody wants. Validation isn’t a bureaucratic hurdle — it’s the fastest path to a business that actually makes money.

    Start with a sharp problem definition. Talk to 20 real potential customers. Build the smallest experiment that can test your riskiest assumption. Ask for money — or at minimum, a firm commitment. Analyze results honestly, and decide with data instead of hope.

    This process won’t guarantee success. But it will dramatically reduce your risk, sharpen your message, and give you a foundation to build on that’s grounded in reality rather than wishful thinking.

    Your next step: write down your riskiest assumption today. Then schedule five customer interviews for this week. Everything else follows from there.

    This article is for educational purposes only and does not constitute financial, tax, or investment advice. Always consult a licensed financial advisor, CPA, or attorney before making financial decisions.

  • LLC Formation for Small Business: Your Complete 2026 Guide

    LLC Formation for Small Business: Your Complete 2026 Guide

    Learn how to navigate the legal complexities of forming an LLC and protect your personal assets, potentially saving you thousands in future liability.

    Starting a new business is exhilarating, but navigating the legal landscape can feel daunting. Many entrepreneurs, especially those launching a small business, often grapple with fundamental questions about legal structure. When James, 47, decided to launch his consulting firm, he initially operated as a sole proprietor, unaware that a single lawsuit could put his home and savings at risk. This common oversight highlights a critical need for proper business structuring.

    According to a 2025 survey by SCORE, a significant portion of new small businesses in the U.S. either delay or misunderstand the importance of selecting the right legal entity. Choosing the correct structure, like an LLC, is more than just a legal formality; it’s a strategic decision that protects your personal assets, offers tax flexibility, and lends credibility to your venture.

    This comprehensive guide will walk you through the entire process of LLC formation for small business owners. You’ll learn what an LLC is, its key benefits, a step-by-step process for setting one up, common pitfalls to avoid, and essential considerations to ensure your business is on solid legal and financial footing from day one.

    What Is an LLC and How Does It Work?

    An LLC, or Limited Liability Company, is a popular business structure in the United States that offers business owners a blend of personal liability protection and operational flexibility. Think of it as a hybrid entity, combining the pass-through taxation benefits of a sole proprietorship or partnership with the liability protection of a corporation.

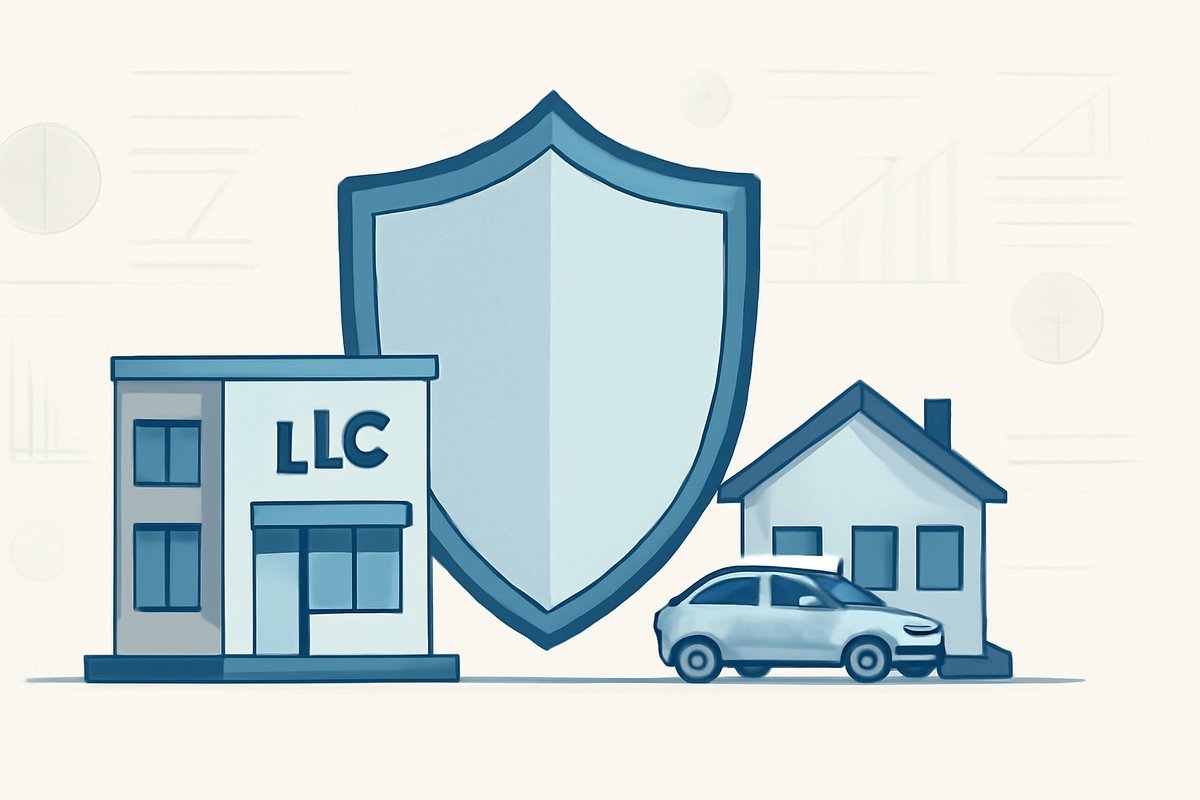
    When you form an LLC, you’re creating a separate legal entity for your business. This separation means that your personal assets — such as your home, car, and personal bank accounts — are generally shielded from your business’s debts and liabilities. If your business faces a lawsuit or bankruptcy, creditors typically cannot pursue your personal property to satisfy business obligations.

    Operationally, LLCs are known for their simplicity. They typically have fewer corporate formalities compared to traditional corporations (C-corps or S-corps), making them attractive for small business owners and startups. For tax purposes, an LLC is a “pass-through” entity by default. This means the business itself isn’t taxed on its profits; instead, the profits and losses “pass through” to the owners’ personal tax returns, where they are reported. This avoids the “double taxation” often associated with C-corporations, where both the corporation and its shareholders are taxed.

    However, LLCs also offer flexibility in how they are taxed. A single-member LLC, by default, is taxed as a sole proprietorship, while a multi-member LLC is taxed as a partnership. Both can elect to be taxed as an S-corporation or even a C-corporation, depending on specific financial and tax planning goals. This adaptability makes the LLC structure suitable for a wide range of businesses, from solo freelancers to small partnerships and family-owned enterprises.

    When the structure of a Limited Liability Company (LLC) first gained widespread acceptance across U.S. states in the late 20th century, it quickly became a preferred choice for small business owners seeking a balance of protection and simplicity.

    Key Benefits of Forming an LLC for Your Business

    Choosing an LLC for your business offers several distinct advantages that can significantly impact your financial security and operational efficiency. Understanding these benefits is crucial for any entrepreneur weighing their options.

    Limited Liability Protection

    This is arguably the most significant benefit of an LLC. As the name suggests, it limits your personal liability for business debts and lawsuits. For example, if your business racks up significant debt or is sued by a client, your personal assets – your house, savings, and other valuables – are generally protected. This separation provides a crucial financial safety net, allowing you to take calculated business risks without jeopardizing your personal wealth. Without an LLC, as a sole proprietor, your personal and business assets are legally one and the same.

    Tax Flexibility

    LLCs offer remarkable tax flexibility. By default, they are taxed as pass-through entities, meaning profits and losses are reported on the owner’s personal tax return, avoiding corporate-level taxation. This simplicity is often ideal for many small businesses. Additionally, an LLC can elect to be taxed as an S-corporation (S-corp) or even a C-corporation (C-corp). Electing S-corp status can be particularly beneficial for some small business owners. The IRS reported that electing S-corporation status for an LLC, when appropriate, could historically result in significant self-employment tax savings for business owners, depending on their salary and profits. This is because, as an S-corp, you can pay yourself a “reasonable salary” subject to payroll taxes, while the remaining profits distributed to you are not subject to self-employment taxes.

    Enhanced Credibility and Professionalism

    Operating as an “LLC” after your business name adds a layer of professionalism and legitimacy. It signals to clients, partners, and lenders that you are a serious, established entity rather than a casual freelancer. This perception can be invaluable when seeking partnerships, securing financing, or attracting higher-paying clients. It makes your business appear more structured and reliable.

    Operational Simplicity

    Compared to corporations, LLCs generally have fewer administrative requirements. They don’t typically require annual board meetings, complex minute-taking, or other formal procedures that corporations often mandate. This reduced burden allows small business owners to focus more on growth and day-to-day operations rather than excessive paperwork, making them a practical choice for many entrepreneurs.

    How to Form an LLC: Your Step-by-Step Guide

    Forming an LLC involves a series of specific steps, primarily regulated at the state level. While the exact requirements can vary slightly from state to state, the general process remains consistent across the U.S. Here’s how to get started:

    1. Choose Your Business Name

      Your LLC must have a unique name that isn’t already in use by another entity in your state. Most states require your business name to include “Limited Liability Company,” “LLC,” or “L.L.C.” You’ll typically need to search your state’s Secretary of State website to check for name availability. Many states also allow you to reserve your chosen name for a short period before formal filing.

    2. Appoint a Registered Agent

      Every LLC must have a Registered Agent. This is an individual or a company designated to receive official legal and tax documents on behalf of your LLC. The Registered Agent must have a physical street address (not a P.O. Box) in the state where your LLC is formed and be available during regular business hours. You can serve as your own Registered Agent, or you can hire a professional service.

    3. File Articles of Organization (or Certificate of Formation)

      This is the official document that formally creates your LLC. You’ll file it with the Secretary of State or equivalent business filing agency in your chosen state. The Articles of Organization typically include your LLC’s name, the address of its principal place of business, the name and address of your Registered Agent, and sometimes the names of the LLC members or managers. The filing fees vary significantly by state.

    4. Create an Operating Agreement

      While not always a legal requirement in every state, an Operating Agreement is a crucial internal document for your LLC. It outlines the ownership structure, members’ rights and responsibilities, profit and loss distribution, management structure, and procedures for decision-making and resolving disputes. Think of it as your LLC’s “bylaws.” Without one, your LLC will be governed by your state’s default LLC statutes, which may not align with your specific business needs or intentions. This agreement is especially vital for multi-member LLCs.

    5. Obtain an EIN (Employer Identification Number)

      The IRS requires nearly all businesses, including LLCs with employees or multiple members, to obtain an Employer Identification Number (EIN) for tax purposes. Even single-member LLCs without employees will need an EIN if they elect to be taxed as an S-corporation or C-corporation, or if they plan to hire employees in the future. You can apply for an EIN online through the IRS website, and it’s typically a quick and free process.

    6. Comply with Other State & Local Requirements

      Depending on your industry and location, your LLC may need additional licenses or permits. This could include general business licenses, professional licenses (e.g., for doctors, lawyers, beauticians), zoning permits, or sales tax permits. Check with your state and local government agencies to ensure full compliance. As part of your initial planning, you might also want to draft a comprehensive business plan, which can guide your LLC’s development and financial projections.

    7. Open a Business Bank Account

      Once your LLC is officially formed and you have your EIN, open a dedicated business bank account. This is critical for maintaining the separation between your personal and business finances, which is essential for preserving your limited liability protection. To ensure your business’s financial health, integrating strong cash flow management strategies from day one is paramount, especially when opening your business bank account.

    Costs, Fees, and Potential Risks of an LLC

    While forming an LLC offers significant advantages, it’s crucial to be aware of the associated costs, ongoing fees, and potential risks. These factors can influence your decision and budgeting.

    Filing Fees

    The initial cost to form an LLC is the state filing fee for your Articles of Organization. This fee varies dramatically by state. For instance, state filing fees for LLC formation can range significantly, from under $50 in some states like Arkansas to over $500 in others, according to various state Secretary of State websites. Some states, like California, also historically had an initial minimum franchise tax due shortly after formation, which adds to the initial outlay.

    Registered Agent Fees

    If you opt to use a professional Registered Agent service instead of serving as your own, you’ll incur annual fees, which typically range from $100 to $300 per year. While an added expense, these services ensure compliance and privacy by handling legal correspondence.

    Annual Fees and Franchise Taxes

    Many states require LLCs to pay annual fees, often called “annual report fees” or “franchise taxes.” These fees ensure your LLC remains in good standing with the state. Like filing fees, these can vary greatly, from a nominal amount to several hundred dollars or more, depending on the state and sometimes the LLC’s revenue. For example, some states have historically imposed higher annual fees or taxes based on factors like an LLC’s gross revenue or number of members.

    Legal and Professional Fees

    While you can form an LLC yourself, many business owners choose to hire an attorney or a business formation service. Legal fees for drafting an Operating Agreement or providing legal advice can range from a few hundred to several thousand dollars, depending on complexity. Business formation services offer a more affordable option for filing paperwork but typically don’t provide legal advice.

    Risk of “Piercing the Corporate Veil”

    The limited liability protection of an LLC is not absolute. If you fail to treat your LLC as a separate legal entity, a court might “pierce the corporate veil” and hold you personally liable for business debts. This can happen if you commingle personal and business funds, fail to keep adequate business records, or don’t adhere to legal formalities. Proper adherence to the rules is essential to maintain your protection.

    Self-Employment Taxes

    Even with an LLC, if you’re a sole proprietor or partner (the default tax treatment), you’re still subject to self-employment taxes (Social Security and Medicare) on your share of the LLC’s profits. While S-corp election can potentially reduce these, you’ll still owe them on your reasonable salary. These taxes can represent a significant portion of your income, so planning for them is critical.

    Common LLC Formation Mistakes to Avoid

    Navigating the LLC formation process can be complex, and certain missteps can undermine the very benefits you’re seeking. Being aware of these common mistakes can save you time, money, and potential legal headaches down the road.

    1. Failing to Create an Operating Agreement

      This is one of the most significant oversights, particularly for multi-member LLCs. While not legally required in all states, an Operating Agreement is crucial. Without it, your LLC will be governed by your state’s default statutory rules, which might not align with your intentions for profit distribution, management responsibilities, or conflict resolution. A well-drafted agreement defines the operational framework and protects members’ interests, preventing disputes and providing clarity.

    2. Commingling Personal and Business Funds

      A common error, often highlighted by legal experts, is failing to maintain separate bank accounts for personal and business finances, a practice that historically jeopardizes the limited liability protection of an LLC. When you mix funds, a court may view your LLC as an extension of yourself rather than a separate legal entity, making it easier to “pierce the corporate veil.” Always keep distinct accounts and funnel all business income and expenses through your business account. Understanding business cash flow management can help you avoid commingling funds.

    3. Not Registering in All Operating States (Foreign LLC Registration)

      If your LLC is formed in one state (your “home” state) but conducts business in another state, you might be required to register as a “foreign LLC” in those additional states. “Doing business” typically means having a physical presence, employees, or generating significant revenue in that state. Failing to register can result in fines, inability to enforce contracts, and loss of limited liability protection in the foreign state.

    4. Ignoring Annual Compliance Requirements

      Many states require LLCs to file annual reports and pay annual fees or franchise taxes to maintain their “good standing.” Missing these deadlines can lead to penalties, late fees, or even administrative dissolution of your LLC by the state. Staying organized and setting reminders for these recurring obligations is essential to avoid losing your liability protection.

    5. Choosing the Wrong Tax Election

      While an LLC offers tax flexibility, making the wrong tax election (e.g., choosing S-corp status when it’s not financially advantageous or failing to make an election when it would be beneficial) can lead to higher tax burdens. For instance, electing S-corp status inappropriately can sometimes lead to increased payroll tax liabilities or scrutiny from the IRS if the “reasonable salary” isn’t justified. It’s crucial to consult with a tax professional to determine the most beneficial tax structure for your specific business situation.

    Alternatives to Consider: Sole Proprietorships and Corporations

    While an LLC is a popular choice for many small businesses, it’s not the only option. Understanding the alternatives — sole proprietorships and corporations — can help you make an informed decision based on your specific needs, risk tolerance, and growth aspirations.

    Sole Proprietorship

    Pros:

    • Easiest and Cheapest to Start: This is the simplest business structure to establish. There’s virtually no formal setup required beyond obtaining necessary business licenses or permits. You and your business are one and the same in the eyes of the law.
    • Full Control: You have complete control over all business decisions.
    • Simple Taxation: Profits and losses are reported directly on your personal tax return (Schedule C of Form 1040), avoiding complex corporate tax filings.

    Cons:

    • No Liability Protection: This is the major drawback. Your personal assets are not separate from your business liabilities. If your business incurs debt or faces a lawsuit, your personal savings, home, and other assets are at risk. The Small Business Administration (SBA) has historically reported that sole proprietorships, while simple to establish, do not provide the personal asset protection that an LLC or corporation offers.
    • Harder to Raise Capital: Lenders and investors often view sole proprietorships as riskier due to the lack of liability protection and formal structure.
    • Limited Life: The business entity is tied to the owner; it dissolves if the owner retires or dies.

    Corporation (C-Corp or S-Corp)

    Pros:

    • Strongest Liability Protection: Both C-corps and S-corps offer strong personal liability protection, legally separating the owners from the business.
    • Easier to Raise Capital (C-Corp): C-corporations are often preferred by investors and venture capitalists because they can issue different classes of stock and are designed for large-scale growth.
    • Perpetual Existence: Corporations can continue to exist even if ownership changes.

    Cons:

    • More Complex and Expensive: Corporations have the most stringent setup and ongoing compliance requirements, including bylaws, board of directors, regular meetings, and extensive record-keeping.
    • Double Taxation (C-Corp): C-corporations are subject to “double taxation.” The corporation pays taxes on its profits, and then shareholders pay taxes again on any dividends they receive.
    • Strict Regulatory Scrutiny: Corporations, especially C-corps, face more regulatory oversight from state and federal agencies.

    Choosing the right structure depends on your business’s specific needs. If personal asset protection is paramount and you desire tax flexibility without excessive formalities, an LLC is often an excellent middle ground. If you’re starting a very low-risk side hustle, a sole proprietorship might suffice. For businesses aiming for significant external investment and eventual public offering, a C-corporation may be the path.

    Frequently Asked Questions About LLC Formation

    How long does it take to form an LLC?

    The time it takes to form an LLC varies significantly by state and depends on the processing times of the Secretary of State’s office. Some states offer expedited processing for an additional fee, which can reduce the wait to a few business days. Standard processing can take anywhere from a few weeks to several months. Online formation services can often expedite the submission process, but the state’s internal processing time remains the primary factor.

    Do I need a lawyer to form an LLC?

    You are not legally required to hire a lawyer to form an LLC. Many entrepreneurs successfully navigate the process themselves using online resources or business formation services. However, if your business involves complex ownership structures, significant investments, multiple partners, or specific legal risks, consulting with an attorney is highly recommended to ensure your Operating Agreement is robust and that your LLC is properly structured for your unique situation.

    Can I be a single-member LLC?

    Yes, absolutely. A single-member LLC (SMLLC) is a very common structure for sole entrepreneurs, freelancers, and consultants. For tax purposes, according to the IRS, a single-member LLC, by default, is treated as a disregarded entity, meaning its profits and losses are reported on the owner’s personal tax return (similar to a sole proprietorship), unless an S-corp or C-corp election is made.

    What’s the difference between an LLC and a corporation?

    Both LLCs and corporations provide limited liability protection, but they differ significantly in complexity, management, and taxation. Corporations (C-corps) are more complex, with strict formalities, boards of directors, and often double taxation. S-corps offer pass-through taxation but still require more corporate formalities than an LLC. LLCs are generally simpler to manage, offer greater tax flexibility (can elect to be taxed as an S-corp or C-corp), and have fewer ongoing compliance requirements, making them more appealing for many small business owners.

    Do I need an EIN if I’m a single-member LLC with no employees?

    By default, if you are a single-member LLC with no employees and do not elect to be taxed as a corporation, the IRS treats you as a “disregarded entity” and you can use your Social Security Number (SSN) for tax purposes. However, you will need an EIN if you decide to elect S-corp or C-corp taxation, if you plan to hire employees, or if your state requires it for certain business licenses or banking purposes. It’s often prudent to obtain an EIN regardless, as it helps separate your personal and business identities.

    Conclusion

    Forming an LLC is a pivotal step for any small business owner seeking to protect personal assets, enhance credibility, and gain tax flexibility. By understanding the straightforward process — from choosing a name and appointing a registered agent to filing your Articles of Organization and creating an Operating Agreement — you lay a robust foundation for your venture. Avoiding common pitfalls like commingling funds or neglecting annual compliance is equally crucial to preserve your LLC’s benefits.

    While the LLC structure offers a compelling balance of protection and simplicity, remember to assess your unique business needs and consider alternatives like sole proprietorships or corporations. Taking the time to properly establish your LLC can safeguard your financial future and allow you to focus on growing your business with confidence. Take the actionable next step: research your state’s specific requirements and consider consulting with a legal or financial professional to tailor the process to your specific situation.

    This article is for educational purposes only and does not constitute financial, tax, or investment advice. Always consult a licensed financial advisor, CPA, or attorney before making financial decisions.